Short answer
Homeowners insurance may cover some cleanup and repair after an unattended death, but delayed discovery raises questions other claims do not. Insurers may examine whether the damage was sudden or gradual, whether the home was vacant, and who holds the policy. Report promptly after discovery, document the timeline, and get an itemized scope that explains why each material must be removed.
Does a homeowners policy pay when a death is found days or weeks later?
It may, at least in part. When someone dies alone and is not found right away, the body's natural changes can damage flooring, subfloor, walls and belongings, and odor can spread through the whole home. Many homeowners and renters policies respond to direct physical damage to property, and an adjuster may treat this damage as part of a covered loss.
What makes unattended death different is the element of time. The damage develops over days or weeks rather than in a single moment, and insurers pay close attention to how a loss unfolded. That does not mean a claim is doomed. It means you should be ready to explain the timeline clearly and to show why the proposed work is necessary.
Policy forms, carrier practices and state rules differ. Ask your insurer how it applies its wording to your situation, and keep the answer in writing.
Why the delay before discovery matters to an insurer
Delay is at the heart of this kind of loss. The longer a person goes undiscovered, the deeper fluids can migrate into building materials and the more rooms odor can reach.
Many homeowners policies exclude losses caused by gradual deterioration, long-term seepage or neglect. An adjuster may ask whether the damage from an unattended death fits the idea of a sudden, accidental event or falls into one of those gradual-loss exclusions. Carriers do not all answer this the same way, which is why the specific wording of your policy matters so much.
Vacancy and occupancy clauses
Some policies also change coverage when a home has been vacant or unoccupied for a set stretch of time. If the person who died lived in the home until their death, the home was generally occupied. Still, ask the adjuster whether any vacancy provision is being considered, especially if the property sat empty for a while after discovery.
Who files the claim when the policyholder is the person who died?
This is one of the most common points of confusion. If the person who died owned the home, the estate usually takes over the policy's rights, and the person appointed as executor or administrator is generally the one who files. Until that person is appointed, a close relative can often report the loss and take steps to protect the property, but the insurer may wait for legal authority before paying.
If the person rented, two policies may be involved. The landlord's policy generally responds to the building, including floors and walls. The tenant's renters policy, if one existed, may respond to personal belongings. Many tenants do not carry renters insurance, in which case the estate may have no coverage for contents at all.
If you are a landlord, notify your carrier as soon as the unit is released. Keep the estate informed about what is being removed, because the tenant's belongings still belong to the estate even when they cannot be salvaged.
Damage that is usually on the table
Unattended death scenes often involve damage beyond the spot where the person was found. Fluids can travel under baseboards, into subfloor and through to a ceiling below. Odor can penetrate drywall, insulation and HVAC ductwork. Insects may have spread through the home. A good remediation scope will describe each of these areas separately so the adjuster can evaluate them one by one.
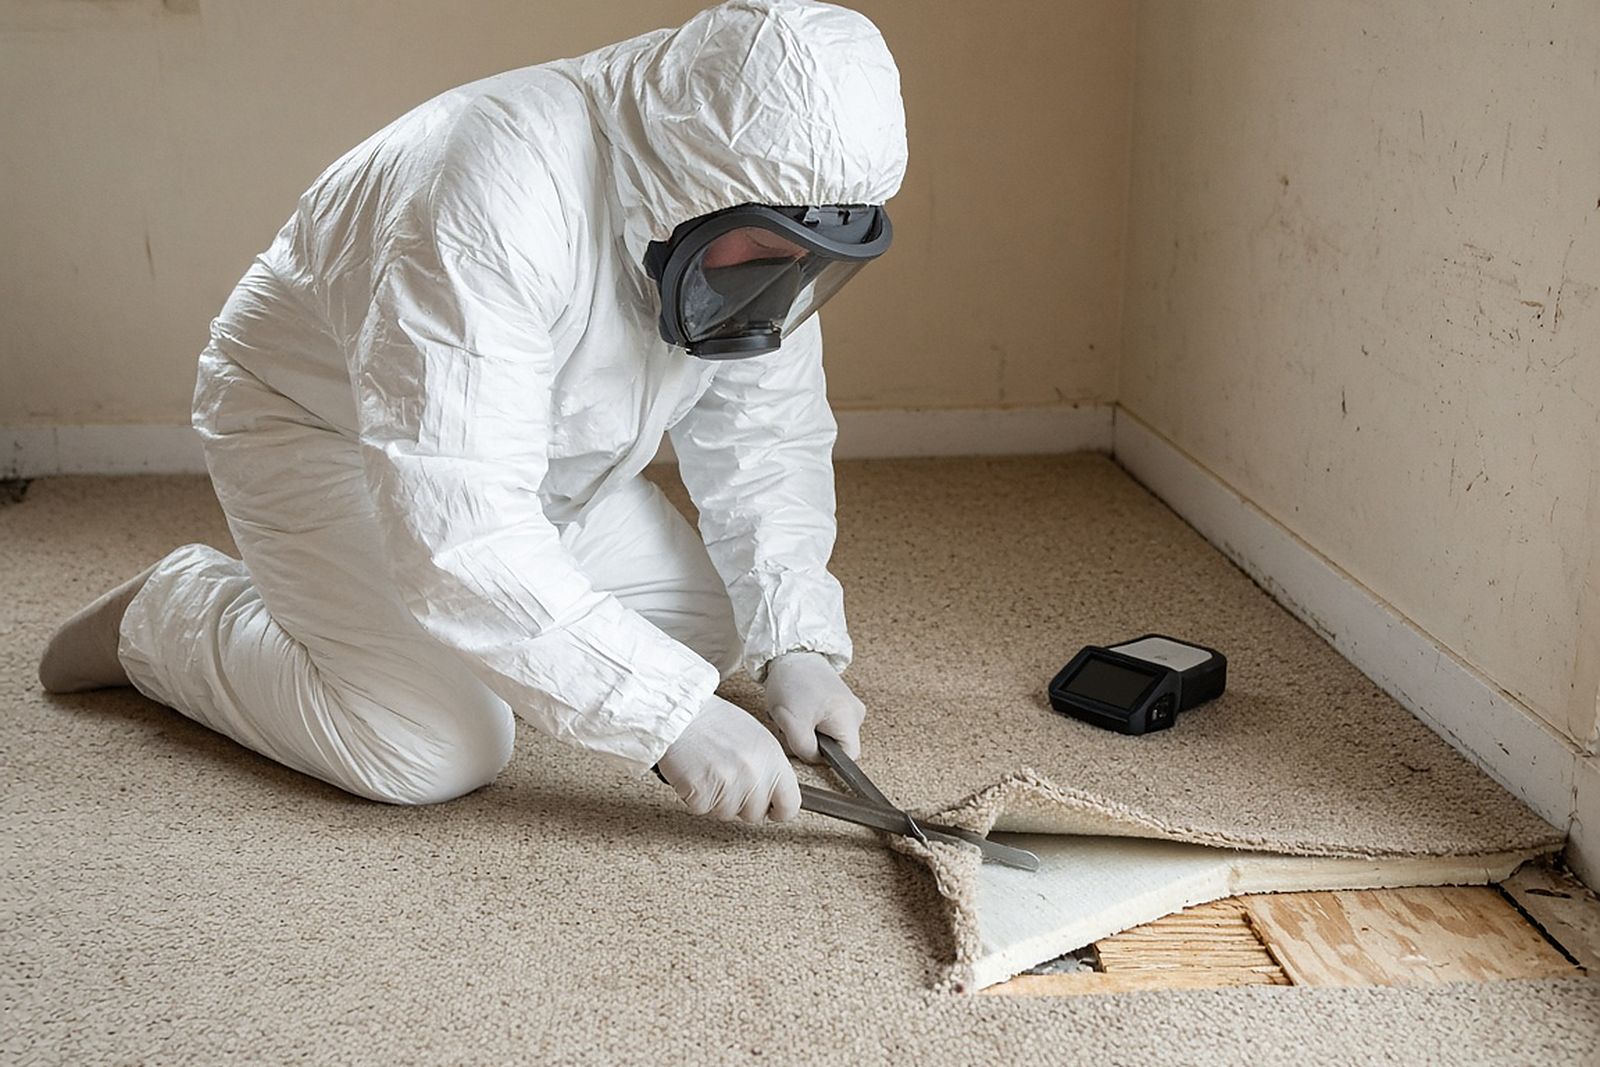
- Flooring, pad, underlayment and subfloor sections that absorbed fluids
- Drywall, baseboard and insulation affected by fluid migration or odor
- HVAC components and ductwork that carried odor through the home
- Furniture, bedding and soft goods that cannot be restored
- Damage to a unit or room below, which may involve a neighbor's policy as well
- Additional living expenses for surviving household members, if the policy includes them
Documentation that helps the adjuster
Build a simple timeline. Write down when the person was last known to be well, when they were found, when police or the medical examiner released the home and when you contacted the insurer. These dates help the adjuster see that you acted promptly once you knew about the loss, which is what most policies require.
Ask the remediation provider to photograph each affected area during assessment and to explain in writing why each material must be removed rather than cleaned. Moisture readings, notes about how far fluids traveled and descriptions of odor sources all support the scope.
Keep receipts for anything you pay while the claim is pending, including lock changes, utilities you keep running and temporary storage for belongings that the family wants to keep.
One claim, step by step
Consider how a claim might unfold for one family. A retired man who lives alone in a house he owns dies of natural causes. His daughter lives in another state. After several days of unanswered calls, she asks a neighbor to check, and the neighbor calls the police. The medical examiner releases the home two days later.
The daughter calls her father's homeowners insurer from out of state, explains what happened and gives the medical examiner's case number. The adjuster explains that the claim will need an estate representative before payment and asks for a written scope. The daughter hires a remediation company, which finds that fluids reached the subfloor in the bedroom and that odor has spread into the hallway and a closet.
The adjuster reviews the scope and asks questions about how long the damage developed. The daughter provides the timeline and the company's photos and notes. The carrier then decides which parts fit the policy and which fall under an exclusion. The daughter asks for the decision in writing and keeps a copy with the estate's records.
This is a composite illustration, not a description of any real claim. Your own outcome will depend on your policy, your carrier and your state.
When the neighbor's unit was damaged too
In apartments, condos and townhomes, an unattended death can affect more than one household. Fluids can seep through a floor into the ceiling below, and odor can move through shared walls and ventilation. When that happens, more than one insurer may become involved.
The neighbor typically reports damage to their own carrier. Their insurer may then seek reimbursement from the building's policy or from the estate, depending on the facts. As the family or estate representative, you do not need to resolve this alone. Share contact information, let the carriers communicate and keep a record of who you spoke with.
A condo or homeowners association may also have a master policy that covers shared structural elements. Ask the property manager for the association's insurance contact early in the process.
What should I watch for when signing with a remediation company?
After an unattended death, families are often far away, grieving and eager to have someone take charge. That makes it important to read the paperwork carefully. Some providers ask you to sign an assignment of benefits that transfers your claim rights to them. Others ask only for a direction to pay, which lets the insurer send payment directly to the company.
Ask what you would owe if the insurer approves less than the estimate. Ask for copies of every document sent to the carrier. A responsible provider will not guarantee coverage and will explain which parts of the work are urgent, such as sealing off odor or controlling insects, and which can wait for adjuster review.
- Is the form an assignment of benefits or a direction to pay?
- Who pays for work the insurer declines?
- Which tasks are urgent, and which can wait for approval?
- Will you provide photos, moisture readings and disposal records?
Where can I turn if the claim is denied?
Ask for the denial in writing, with the specific policy language quoted. Compare it to the scope and ask the adjuster which facts led to the decision. If you believe the decision is wrong, many carriers have an internal review, and your state insurance department can explain complaint options. An attorney who handles insurance or estate matters can also advise the executor.
Be gentle with yourself
Finding someone who died alone brings its own particular sorrow, often mixed with guilt about not knowing sooner. Please be gentle with yourself. Delayed discovery happens in close, loving families too, and handling the practical side carefully is itself an act of care for the person you lost.